MTD ITSA for Contractors: Your Tax Life Just Got 5x More Complicated
· SF Admin
UK contractors operating through a Ltd Co face the largest tax compliance shift in three decades. If your structure includes personal Self Assessment, dividends, IR35 contracts, or property, here's exactly what changes — and how to keep your accountancy fees from doubling.
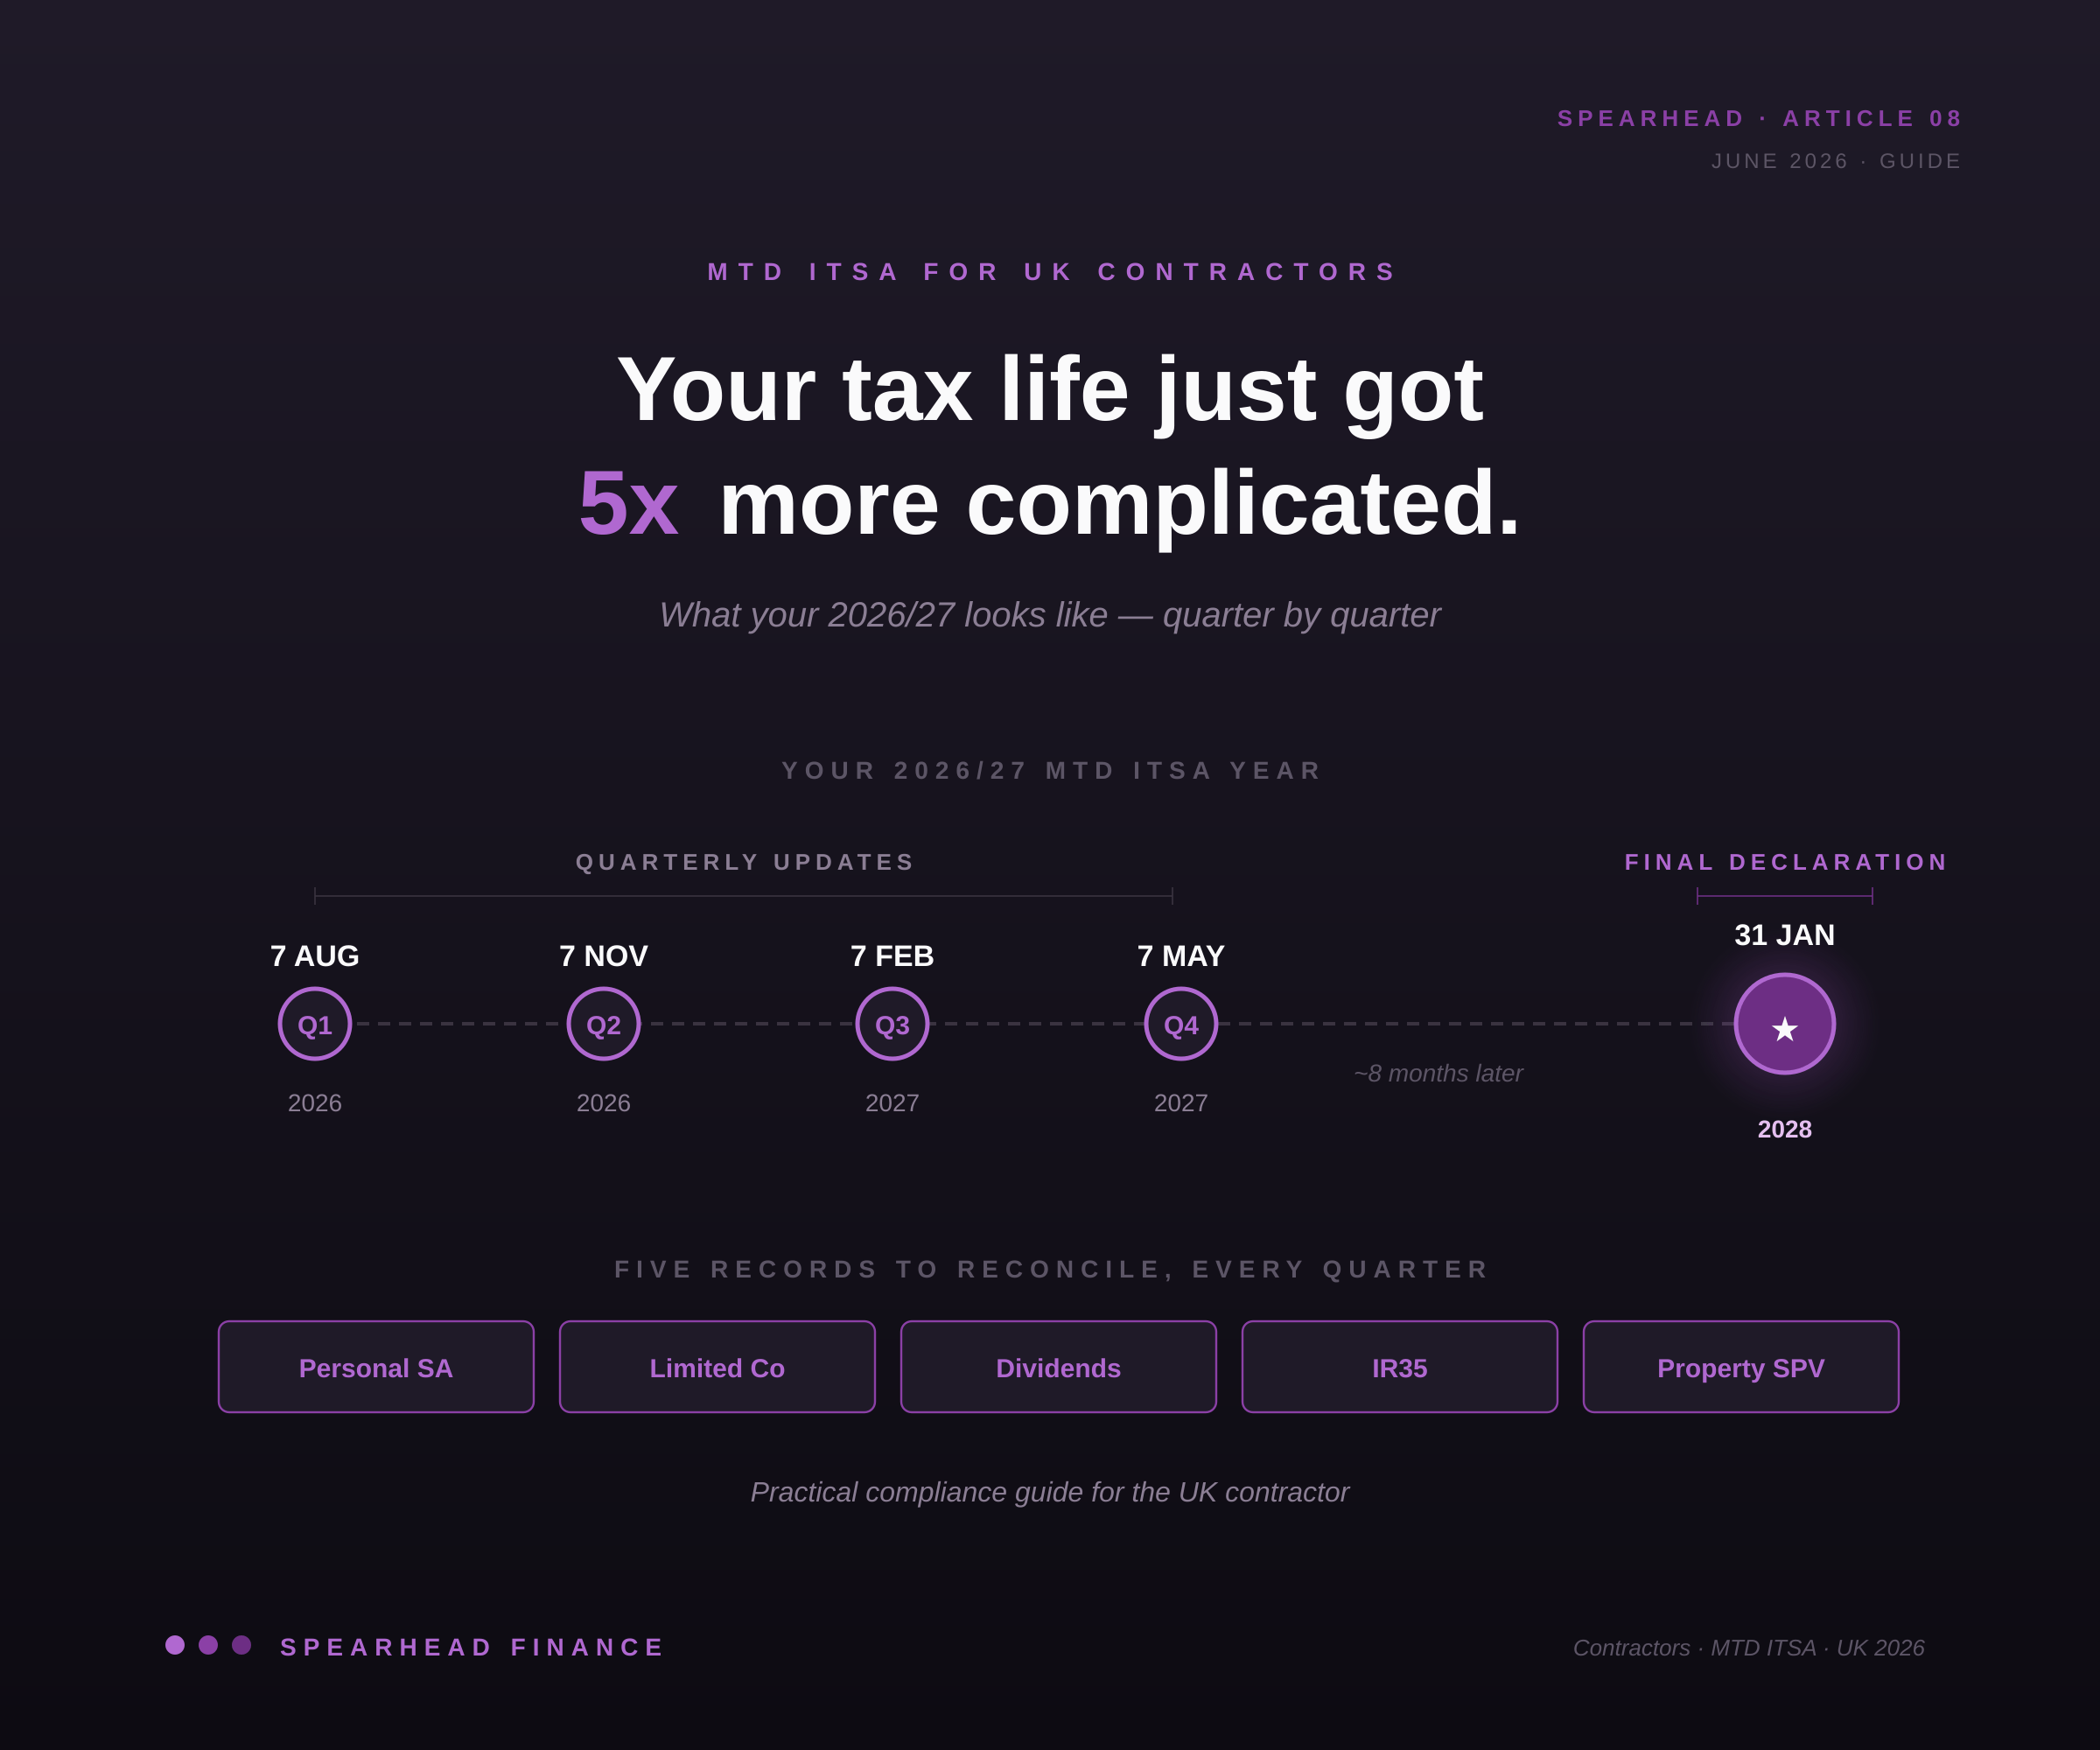
If you're a UK contractor reading this — operating through your own limited company, billing for day-rate work, paying yourself a mix of salary and dividends — your tax life has just become materially more complicated. As of 6 April 2026, Making Tax Digital for Income Tax Self Assessment (MTD ITSA) is live. For most contractors with personal income above £50,000 a year, that means filing four quarterly updates to HMRC instead of one annual Self Assessment, keeping digital records in compatible software, and producing a final declaration at year-end. Five touchpoints with HMRC where there was one. Hence the headline: 5x more complicated. This guide explains what's actually changed for contractors specifically — including the multi-entity reality that the generic MTD ITSA coverage tends to skim over — and the practical steps to stay compliant without doubling your accountancy fees. For the broader regulatory context, see the pillar guide . For the deeper thinking on multi-entity tax positions, see Your tax position is one thing, not four . 1. Do contractors need to comply with MTD ITSA? Yes, almost certainly — if your personal income (salary plus dividends from your Ltd Co, plus any property income held in your own name, plus any other self-employment income) exceeds the threshold for the tax year. From April 2026, that threshold is £50,000. From April 2027, £30,000. From April 2028, £20,000. Two clarifications that catch contractors out: The threshold applies to your personal income, not your company's turnover. Your Ltd Co's revenue could be £200,000 and your personal salary + dividends could still be below the threshold (if you take most profit as retained earnings). What matters is what you personally receive — salary, dividends, any property income held in your name. Your Limited Company itself is not in MTD ITSA scope. The Ltd Co files corporation tax (CT600) on a separate cycle. MTD for Corporation Tax is somewhere in HMRC's medium-term roadmap, but for now your Ltd Co continues with its annual cycle. What goes into MTD ITSA is your personal tax position — including the dividends and salary your Ltd pays you. For the vast majority of professional contractors — anyone billing £400 a day or more, anyone with two-plus years of consistent contracting income — the answer is yes. You're in scope from April 2026. 2. How MTD ITSA changes for contractors specifically Most MTD ITSA coverage treats the typical taxpayer as a sole trader: one business, one set of books, one Self Assessment. Contractors are not sole traders. Contractors operate a corporate structure — usually a limited company, sometimes with property holdings in a separate SPV, sometimes with multiple income streams (outside-IR35, inside-IR35, other). What this means in practice: a contractor's compliance burden under MTD ITSA isn't 5x; it's roughly 5x per entity . Each entity you operate has its own records, its own bookkeeping platform, its own submission requirements. The new work isn't just the four quarterly updates. It's the reconciliation across multiple entities every quarter, where previously this reconciliation happened once a year at Self Assessment time. There's a structural name for the work that lives in the gap between your bookkeeping platforms and your final declaration: the synthesis gap . It is the work most contractors thought they were paying their accountant to do, and increasingly are. Quarterly cycles have multiplied the volume of that work without (yet) multiplying the fee. 3. Your five tax records, explained The typical professional contractor in 2026 has five distinct tax records flowing into a single personal position. Each needs its own MTD-compatible record-keeping. Each interacts with the others in ways that need reconciling. Here they are. 1. Your personal Self Assessment. Salary received from your limited company. Dividends declared by the Ltd and received by you. Any savings interest, capital gains, side income. This is the record that's in MTD ITSA scope from April 2026 onwards, and the one that requires the quarterly updates. 2. Your trading limited company. Corporation tax (CT600), payroll records, director loan account, dividend declarations. Not in MTD ITSA scope — it's corporation tax, filed annually. But the dividends declared by the Ltd flow into your personal SA, so the two records must reconcile. 3. Dividends. Declared by the Ltd, received by you personally. Reported on your final declaration. Eats into your higher-rate bands. The most common reconciliation error: the dividends declared (in the Ltd) and the dividends reported (on your personal SA) drift apart year-to-year. 4. IR35 contracts. If you've taken any inside-IR35 work, the deemed payment treatment applies. The end client (or fee-payer) deducts tax and NI before passing the net amount through your company, and the deemed payment flows into your personal income tax computation. It does not get taxed twice, but the reconciliation needs to be precise. 5. Property SPV (if applicable). A buy-to-let held in a separate property company is its own entity — its own CT600, its own books, its own bank account. Property income held in the SPV doesn't count toward your personal MTD ITSA threshold, but the dividends from the SPV do. Property held in your personal name (not in an SPV) counts directly and is in MTD ITSA scope from the first wave. Five records. Every one of them is you . None of them lives in the same system as the others. 4. What MTD ITSA quarterly updates look like for a contractor For each quarter in scope, you submit aggregated totals to HMRC for your personal income. The categories — income totals and expense totals by type — are HMRC-prescribed. The format is structured data sent via MTD-compatible software's connection to HMRC's API. For a typical contractor, what's actually in each quarterly update: Self-employment income (any direct sole-trade work; for most contractors this is zero because they trade through a Ltd) Property income (rental income from any properties held in your personal name; net of allowable expenses) Expenses in the standard HMRC categories (where applicable) What's not in each quarterly update: Your Ltd Co's revenue or profit (separate, on the CT600) Dividends received (these go in the final declaration) IR35 deemed payments (these go in the final declaration) Anything from your SPV (separate) The deadlines for tax year 2026/27 are: Quarter Period Deadline Q1 6 April – 5 July 2026 7 August 2026 Q2 6 July – 5 October 2026 7 November 2026 Q3 6 October 2026 – 5 January 2027 7 February 2027 Q4 6 January – 5 April 2027 7 May 2027 Final declaration 2026/27 tax year 31 January 2028 Use the MTD deadline calculator for your specific situation if you've made any elections. 5. Why most contractor accountancy fees are about to rise Pre-MTD, a typical UK contractor accountancy package covered: annual Ltd Co accounts and CT600, annual Self Assessment, monthly bookkeeping support, payroll, dividends, occasional advice. Typical price: £100–£250 per month, or £1,200–£3,000 per year. Post-MTD, the same package has to cover all that plus four quarterly MTD ITSA updates, plus the reconciliation work to make sure those updates align across your entities. That work is real and isn't going away. The question for your accountancy firm is whether they absorb the increased cost, re-price you, or lose you. Three responses are emerging in the market: Some practices absorb. They're hoping efficiency gains from new software will catch up before the margin compression becomes unsustainable. This may or may not work. Some practices re-price. Mid-year fee discussions that didn't happen pre-2026 are happening now. Expect a 30–60% increase if your accountancy firm is going down this path. Some practices restructure. Per-client wholesale licensing models (the kind Spearhead's Practice Tier sells to accountants) allow firms to keep the client price flat while reclaiming the reconciliation time. If your accountant mentions a "synthesis layer" or "per-client wholesale," that's what they mean. Ask your accountant explicitly: "Will my fee change in 2026/27 because of MTD ITSA?" It's the conversation worth having now, before the year is too far in. 6. The software options for contractors specifically This is covered in more depth in the software comparison article ; the short version for contractors: For single-entity contractors (one Ltd, no property, simple income), almost any MTD ITSA-compatible bookkeeping platform works: Xero, QuickBooks, FreeAgent (free with NatWest banking), Coconut (free with Zempler). Pick one, use it for the Ltd, file your personal SA through your accountant or directly. For multi-entity contractors (Ltd + personal SA + dividends + IR35 + property SPV), no incumbent bookkeeping platform was built for your situation. Each operates per-entity. You either reconcile manually (in Excel), have your accountant reconcile (and pay for it), or use a synthesis layer. The synthesis layer is what TaxSync Plus does: it ingests data from your bookkeeping platforms, holds your multi-entity position as a single beneficial-owner view, and produces MTD ITSA submissions from the synthesised data. £75/month, with 50% off your first month. It's purpose-built for the contractor scenario. Total tooling cost for a multi-entity contractor using bookkeeping + synthesis: Bookkeeping (Xero or similar): ~£28/month TaxSync Plus: £75/month Combined: ~£103/month, or £1,236/year Compared with the £1,500–£2,000 of accountancy reconciliation work the same setup replaces, the maths usually works out in your favour by year two — provided your structure is genuinely multi-entity. For single-entity contractors, the synthesis layer is overkill. 7. A step-by-step compliance walkthrough For a typical multi-entity contractor entering MTD ITSA, the practical workflow: Step 1: Confirm you're in scope. Income above £50,000 from personal sources (salary + dividends + property held personally) in your most recent return = in scope from April 2026. If unsure, check the readiness quiz . Step 2: List your entities. Personal SA. Trading Ltd. Property SPV (if any). Any inside-IR35 contracts. Any side income. Write them down. This is the basis of everything else. Step 3: Confirm each entity has MTD-compatible bookkeeping. Your Ltd Co almost certainly already has bookkeeping in Xero, QuickBooks, FreeAgent or similar. Check that it's MTD ITSA-recognised (it almost certainly is). For your personal SA, you'll need either an MTD-compatible tool, your accountant's submission service, or a synthesis layer. Step 4: Decide on your synthesis approach. Either: (a) your accountant does the reconciliation manually (the £1,500–£2,000/year expense), (b) you do it yourself in Excel (free but error-prone and time-consuming), or (c) you use a synthesis layer like TaxSync Plus. Step 5: Set up bank feeds. Each entity's bookkeeping needs its bank feed. Plus your personal accounts for the personal SA component. Allow a week for feeds to stabilise before relying on them. Step 6: Categorise the current quarter's transactions. Most modern tools auto-categorise; review and correct anything the rules got wrong. The categorisation work pays off across all four quarters of the year. Step 7: Submit your first quarterly update by 7 August. This is the one most contractors stumble on. The August deadline arrived faster than people expected, and the first submission always reveals the bookkeeping gaps. Submit even if imperfect; you can amend later. Step 8: Repeat for Q2, Q3, Q4. Each cycle gets faster as your categorisation rules and reconciliation patterns mature. Step 9: Final declaration by 31 January 2028. This is your full personal tax return — consolidating the quarterly figures with dividends, IR35 income, and everything else. Most contractors hand this off to their accountant. 8. Common contractor mistakes and how to avoid them In rough order of frequency, the mistakes that catch contractors out: Assuming your Ltd Co is in MTD ITSA scope. It isn't. The Ltd files CT600 annually as before. Only your personal income from the Ltd is in MTD ITSA scope. Not reconciling Ltd dividends to personal SA. The dividends declared in the Ltd's accounts and the dividends reported on your personal SA need to match. Discrepancies trigger enquiries. Forgetting IR35 deemed payments. If you had inside-IR35 work, the deemed payment treatment needs to flow into your personal SA computation. Easy to miss when the income arrives in your Ltd's bank account looking like normal Ltd income. Mixing personal and Ltd Co bank accounts. Always a no-no for tax purposes. Now penalised harder under MTD ITSA because the audit chain is more rigorous. Missing the 7 August deadline. It's the first one. Contractors who used to file Self Assessment in late January aren't yet in the muscle memory of an August deadline. Set the reminder now. Buying software that doesn't actually file. Some bookkeeping tools record transactions but don't submit to HMRC. Always check the HMRC MTD ITSA-compatible software list before signing up. Trying to keep doing it all in Excel. Allowed for very simple cases with bridging software, but for multi-entity contractors, the manual reconciliation work compounds across four quarters per year. Not telling your accountant about all your entities. Particularly common with SPVs and inside-IR35 work that came mid-year. Your accountant can only reconcile what they know about. 9. Action checklist: what to do this month, next month, next quarter If you're a contractor reading this in mid-2026 and you haven't yet started: This week: Confirm income above threshold (use the readiness quiz ) List your entities (Ltd, SPV, IR35 contracts, property in personal name) This month: Choose your software (bookkeeping per entity + synthesis layer or accountant) Connect bank feeds to each bookkeeping platform Categorise the current quarter's transactions By the next quarterly deadline: Submit your quarterly update on time Note what was painful in the workflow — that's the part to automate next quarter By 31 January 2028: Final declaration filed for 2026/27 tax year Reconciliation review with your accountant Year-two plan written (now that you've done one full cycle) FAQ Do I need MTD ITSA if my Ltd Co's turnover is below the threshold? The threshold applies to your personal income, not your Ltd's turnover. If your personal income (salary + dividends + property held personally) is above the threshold, you're in MTD ITSA scope regardless of the Ltd's turnover. Does dividend income count toward the MTD ITSA threshold? Yes. Dividends declared by your Ltd and received personally count toward your personal income for threshold purposes. What if I'm inside IR35? Inside-IR35 income flows through your Ltd into your personal income via the deemed payment treatment, and counts toward your personal MTD ITSA threshold. The IR35 reporting itself is unchanged by MTD ITSA — what's changed is how the resulting personal income is reported quarterly. Can my accountant file MTD ITSA on my behalf? Yes. The agent authorisation framework (the 64-8 mandate) extends to MTD ITSA. Your accountant uses their existing agent credentials to submit on your behalf, exactly as with the previous Self Assessment regime. Do I need separate software for my personal SA and my Ltd Co? Effectively yes. Your Ltd's bookkeeping lives in a per-entity tool (Xero, QuickBooks, FreeAgent). Your personal SA needs either its own MTD-compatible tool, your accountant's submission service, or a synthesis layer that consolidates across both. How does MTD ITSA affect my IR35 reporting? IR35 status determination and the deemed payment calculation don't change. What changes is that your personal income — including IR35 deemed payments — is now reported quarterly through MTD ITSA, not annually through Self Assessment. What if I have multiple Ltd Cos? Each Ltd is a separate entity for corporation tax. Your personal income from each (salary, dividends) all aggregates into your single personal SA for MTD ITSA. The reconciliation across multiple Ltds is one of the strongest cases for a synthesis layer. Can my spouse and I split MTD ITSA between us? Joint income (joint property, for example) is split by the agreed beneficial-ownership share. Each spouse's share counts toward their individual MTD ITSA threshold. The two spouses file separately. What to do next If you've read this far and are running a multi-entity contractor structure, the immediate action is clear: you need a synthesis layer, or your accountancy fees will be the ones absorbing the cost. TaxSync Plus is £75 a month, with 50% off your first month — designed specifically for the contractor scenario described in this article. Start your TaxSync Plus subscription → If you want to think it through more carefully first: the readiness quiz takes two minutes and gives a tailored recommendation. The editorial piece on the same topic covers the conceptual ground at depth. If you're still on the fence, the maths is straightforward: a multi-entity contractor pays ~£1,500–£2,000 a year in accountancy reconciliation. TaxSync Plus is £750 a year on annual billing. The break-even is in the first year, before factoring in the time you stop spending on month-end reconciliation yourself. The tax life of a UK contractor in 2026 is 5x more complicated than it was in 2025. The tools have to catch up. They're starting to.